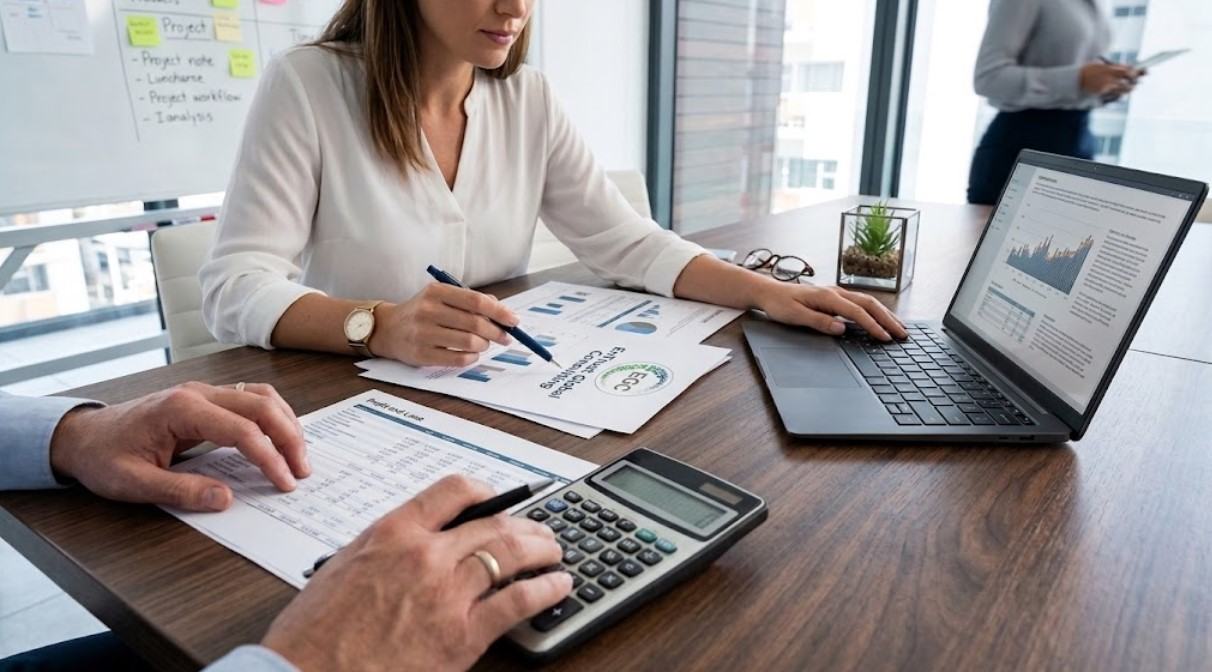
Running a business comes with a long list of priorities, and bookkeeping often gets pushed to the bottom of that list. Many owners assume they can keep track of everything in their head or catch up on the paperwork later, especially when things feel busy or the business still feels small enough to manage informally.
The businesses that scale smoothly, though, are usually the ones that treat their financial records as a priority rather than an afterthought. Why accurate bookkeeping matters for growing businesses becomes clear the moment a company applies for financing, faces a tax review or simply tries to understand where its money is actually going.
Bookkeeping is the ongoing process of recording every financial transaction a business makes, from sales and purchases to payroll and everyday expenses. It is not the same as accounting, which interprets this data to guide strategy. Bookkeeping is the raw material accountants and business owners rely on to make sound decisions.
When records are accurate, every dollar coming in and going out is tracked, categorised and reconciled against bank statements. When they are not, even simple tasks like filing taxes or applying for a business loan become stressful and time consuming.
As a company grows, transactions multiply, staff numbers increase and cash flow becomes harder to track by memory alone. This is exactly why accurate bookkeeping matters for growing businesses more than it does for a business that has just started out. Growth brings complexity, and complexity without organised records leads to costly mistakes.
A growing business also attracts more scrutiny, whether from banks, investors or tax authorities. Clean books signal that a company is well managed and worth trusting with capital or contracts.
One of the biggest reasons why accurate bookkeeping matters for growing businesses is the clarity it brings to daily operations. Owners who know their numbers can answer questions like these without guesswork.
Are we actually profitable this quarter
Which products or services generate the most margin
Do we have enough cash to hire another employee
Are our expenses trending in a direction we can sustain
Without reliable records, these questions get answered with gut feeling rather than data, and gut feeling is a risky way to run a business.
Every business is expected to maintain organised financial records that can be produced when a tax authority asks for them. Accurate bookkeeping keeps a company ready for that request at all times instead of scrambling before a deadline.
Missed filings, incorrect deductions and disorganised invoices are among the most common reasons businesses face penalties. Regular reconciliation and proper categorisation of transactions reduce this risk significantly, and they make working with an accountant far less painful when tax season arrives.
Cash flow problems are one of the leading reasons small and mid sized businesses struggle, even when they are technically profitable on paper. Bookkeeping gives owners real time visibility into receivables, payables and upcoming obligations.
Recording transactions daily: Prevents backlog and keeps financial data current.
Reconciling accounts monthly: Catches errors and discrepancies early.
Tracking receivables closely: Reduces late payments and cash flow gaps.
Separating business and personal finances: Improves reporting accuracy.
Using cloud accounting software: Enables real-time financial visibility.
This kind of consistency is part of why accurate bookkeeping matters for growing businesses that want to avoid liquidity surprises during expansion phases.
Lenders and investors do not fund businesses on promises alone. They want to see profit and loss statements, balance sheets and cash flow reports that reflect the true state of the company. A business with organised books can move through due diligence faster and present itself as a lower risk investment.
This is another reason why accurate bookkeeping matters for growing businesses that plan to raise capital, apply for a loan or bring on new partners in the near future.
Many businesses run into trouble not because they ignore bookkeeping entirely, but because they handle it inconsistently. Some of the most frequent mistakes include the following.
Mixing personal and business expenses in the same account
Delaying data entry until month end or later
Failing to reconcile bank statements regularly
Misclassifying expenses under the wrong categories
Relying on memory instead of documented records
Each of these mistakes seems small on its own, but together they create a financial picture that cannot be trusted for planning or compliance.
Bookkeeping is not just about staying out of trouble with tax authorities. It is a strategic tool that helps businesses understand profitability, plan for expansion and set realistic goals. Owners who review their books regularly are better positioned to spot underperforming areas early and double down on what is working.
Over time, this habit compounds. A business that has a full year or several years of clean financial history has a much clearer benchmark for measuring progress than one that starts fresh every reporting period.
Handling bookkeeping internally works well for very small operations, but as transaction volume grows, so does the risk of errors. Many businesses choose to outsource bookkeeping and accounting functions once they realise that professional support saves more money than it costs, through fewer errors, better tax positioning and time freed up for actual business operations.
Good financial habits rarely feel urgent until the moment they are needed most, whether that is during a tax review, a funding round or a difficult cash flow month. Building those habits early is exactly why accurate bookkeeping matters for growing businesses that want to scale without unnecessary financial stress.
If you are looking to strengthen your financial foundation, businesses can learn more from EGC Consulting about how structured bookkeeping and accounting support is delivered. For guidance tailored to your specific situation, contact our team to discuss how professional bookkeeping support could work for you.
Why Tax Compliance Matters for Business Growth and Trust: How staying on top of tax obligations builds credibility with regulators and stakeholders.
Internal Audit and Risk Management A Basic Guide: A look at how internal audits catch control gaps before they turn into costly problems.
What Is ESG Reporting and Why Businesses Need It Now: An introduction to ESG reporting and why more companies are being asked for it.
7 Signs Your Small Business Has Outgrown DIY Bookkeeping: Warning signs that spreadsheet bookkeeping is no longer enough for a growing business.
7 Benefits of Outsourcing Accounting Services in UAE: Why more founders and finance managers are choosing outsourced accounting as their business grows.
Your trusted partner for strategic advice and managed services in Finance, IT and Tax Excellence.
© 2025 EnTrust Global Consulting. All Rights Reserved.